United States video game console sales tumbled to their weakest August in more than a decade, with market researcher Circana reporting that hardware volume fell 15% from a year earlier to just 559,000 units. According to Circana analyst Mat Piscatella, the figure marks the lowest August total since 2013—when only 423,000 consoles changed hands—and reflects a broad-based slowdown across Sony, Microsoft, and Nintendo as elevated prices, market saturation, and frontloaded demand converged on one of the traditionally quiet months of the gaming calendar.
The decline was felt most acutely by Microsoft. Xbox unit sales dropped 31% year-over-year to their lowest August figure since 2020, while PlayStation hardware slipped 11% compared with a year ago and Nintendo’s numbers fell 15% relative to August 2025. Taken together, the three major platforms posted a sharp contraction in units sold even as the money flowing into the category tells a more complicated story.
The Price Paradox: Fewer Units, More Revenue
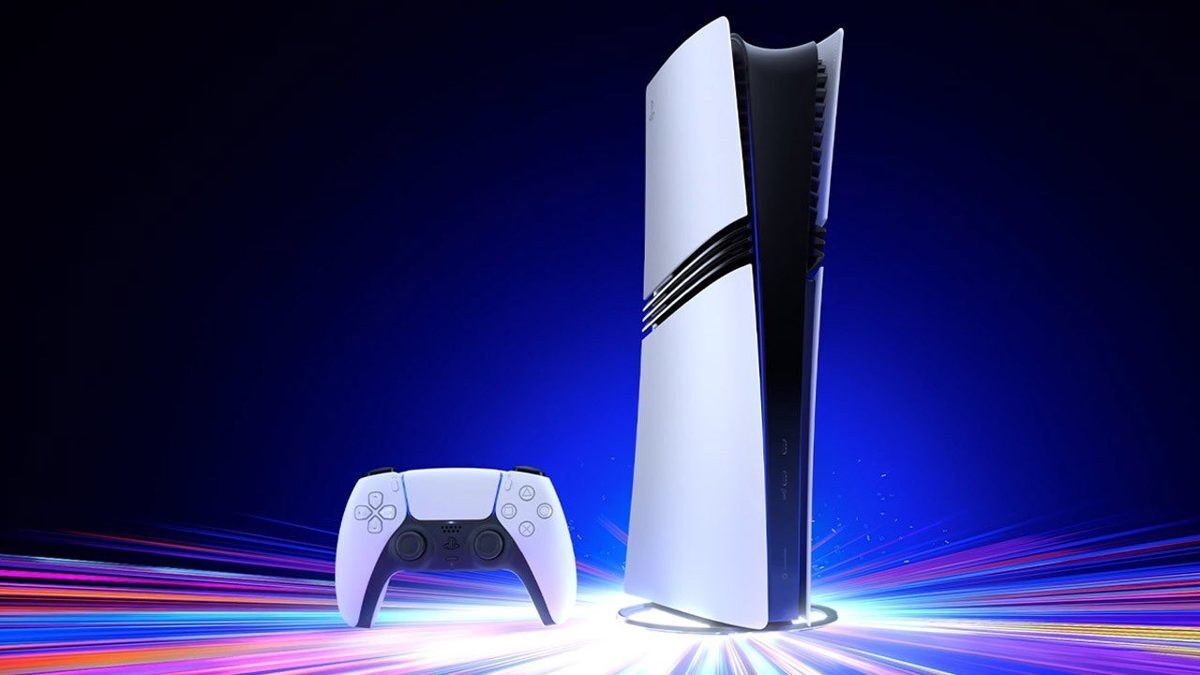
For the manufacturers building these machines, there is a silver lining buried within the soft volume numbers. Higher hardware prices have lifted the average selling price from $476 in 2025 to $541 in 2026, meaning consumers are now paying considerably more for fewer consoles on the market. Current console prices sit at historical highs rather than lows, driven by sustained global component pressure and mid-generation upgrades such as the $900 PS5 Pro, which pulls the category’s average price sharply higher.

In essence, buyers are purchasing fewer units because the entry barrier is much higher than in previous console cycles. After roughly six years on sale, market saturation has likely set in for both the Xbox Series X|S and PS5 lineups, while hardware price increases implemented earlier in 2026 triggered a massive buying wave as consumers rushed to get ahead of the hikes. That frontloaded demand subsequently drained potential summer console purchases from the pipeline.
The data shows that even as unit volume dropped, dollar sales can still climb when buyers trade up into premium hardware—a reminder that revenue and volume are increasingly diverging in this generation.
Circana analyst Mat Piscatella
Sony illustrates the point most clearly. Despite an 11% drop in unit volume, the company’s dollar sales actually grew 17% year-on-year, buoyed by stronger demand for its higher-tier hardware models.
A Generation Without a Horizon
The current contraction carries historical echoes that gamers will recognize. August 2013 can be viewed as the twilight phase of the PS3 and Xbox 360 era, when enthusiasts saved their cash in anticipation of the PS4 and Xbox One—both launched in November 2013. Yet this cycle looks markedly different: no successor machines have been officially unveiled, and hardware sales have slowed despite a mid-generation push rather than being propped up by an imminent next-gen reveal.
The games market, meanwhile, offered some bright spots amid the softness in hardware. NBA 2K27 was unsurprisingly the best-selling game of August and stands as the third-best-selling title of 2026 so far. Madden NFL 27 finished as the second-best-selling game of the month, while Elden Ring climbed to seventh place—up from No. 41 in July—after receiving a Switch 2 port.
The Physical Software Shift
Across the broader software category, spending on new physical media rose 5% year-over-year for the first several months of 2026, reaching $738 million. A major driver was Switch 2 Game-Key Card releases, which surged an astonishing 631%, more than offsetting a 3% decline in spending across all other new physical media formats.
Traditional discs and full-data cartridges continue their steady multi-year decline as players increasingly move to digital storefronts. But because Game-Key Cards represented only a small slice of the physical market in 2025, publishers’ sudden adoption of the format in 2026 produced that dramatic percentage jump—enough dollar volume to push total physical software spending into positive territory and further obscure the ongoing erosion of disc- and cartridge-based media.
Looking Ahead
Content spending as a whole, however, softened. Total content revenue fell 10% year-over-year to $3.8 billion, bringing year-to-date content spending down 2% to $32.2 billion. Mobile experienced the steepest decline, with spending dropping 18% compared with a year earlier, while console content sales slipped 7%. PC gaming stood out as an anomaly: platform spending grew 13% year-over-year, and subscription purchases rose 3%, underscoring the continued strength of the personal computer segment even as hardware volumes cool.
With no next-generation consoles on the horizon and current machines well into their sales lifecycle, analysts will be watching whether the price-driven revenue gains can sustain publishers through a period of declining unit volume—or whether the gap between what consumers pay and how many units move continues to widen in the months ahead.




Join the conversation